Nonprofit CPA services for healthcare nonprofits.
Accounting infrastructure built for the revenue complexity healthcare nonprofits carry.
18+
years of nonprofit-exclusive practice
500+
nonprofit clients served
60+
nonprofit professionals
95%+
client retention rate
Grant funding, reimbursement & program reporting.
Healthcare nonprofits manage a blend of grant funding, reimbursement revenue, and program-based reporting that funders expect broken out clearly. Revenue from each source follows its own recognition rules, and financial reporting has to satisfy both board and funder format requirements simultaneously.
Community health centers often layer federal grant funding on top of patient-service reimbursement and philanthropic support, reconciling three distinct revenue-recognition approaches within a single fiscal year. Han Group builds the accounting infrastructure to handle that reconciliation accurately from the first month of an engagement.
Audit. Accounting. Tax.
Audit & assurance.
Financial statements that satisfy both board governance and funder accountability requirements.
Client accounting & advisory services (CAAS).
Accounting infrastructure that reconciles grant, reimbursement, and program revenue into one view.
Tax services.
Form 990 preparation and compliance for organizations with mixed nonprofit revenue sources.
Aligned to your revenue mix.
Each revenue source follows its own recognition rules. The accounting infrastructure has to accommodate all of them, and the reporting has to satisfy both your board and your funders.
Financial statement preparation.
Statements prepared under GAAP and FASB ASC 958, reflecting your organization’s specific fund structure.
Revenue recognition.
Grant and reimbursement revenue recognized under the applicable rules for each funding source in your mix.
Program-based reporting.
Financial reporting built to each funder’s requirements, program by program.
Audit & Form 990.
Annual audit and Form 990 preparation grounded in the same nonprofit-sector depth as every other engagement.
Internal controls.
Control frameworks calibrated to your organization’s structure, staffing, and revenue-processing requirements.
From revenue mapping to ongoing reporting.
01
Current-state accounting review.
We assess your existing books, revenue mix, and reporting obligations to establish a baseline.
02
Chart-of-accounts alignment.
We map which recognition rules apply to each funding source, so reconciliation is built into the system from setup.
03
Reporting cadence setup.
We build a reporting rhythm that serves both your board and your funders on the cadence they expect.
Nonprofit accounting from the start, not a retrofit.
Every engagement is nonprofit work because nonprofit work is the only work we do. For healthcare nonprofits, that means 18 years of GAAP and FASB ASC 958 fluency applied to your revenue mix. Donor-restriction tracking is where we start, and grant, contract, and reimbursement revenue each get classified on their own terms.
The right financial partner starts here.
If your organization needs a financial partner who starts from nonprofit accounting standards rather than a for-profit healthcare framework, we can start with a conversation about your revenue structure.
Who we work with.
Han Group works exclusively with nonprofits. Every engagement we take on deepens the sector knowledge that benefits every client we serve.
Trade associations & memberships.
501(c)(6) organizations navigating dues-cycle revenue, lobbying disclosure, and association-specific governance.
Foundations.
Private and family foundations navigating excise tax, self-dealing rules, and minimum distribution requirements.
Higher education.
Universities and colleges carrying endowment complexity and federal financial aid compliance.
National Nonprofits.
Major charities managing multi-program operations, functional expense allocation, and rating-agency scrutiny.
The Nonprofit
Leadership Exchange.
Nonprofit leaders learn most from each other. The Exchange is Han Group’s forum for that: webinars, peer roundtables, and board governance education for executive directors, senior staff, and board members.

The latest from Han Group.
Published perspective and upcoming programming for nonprofit finance leaders.
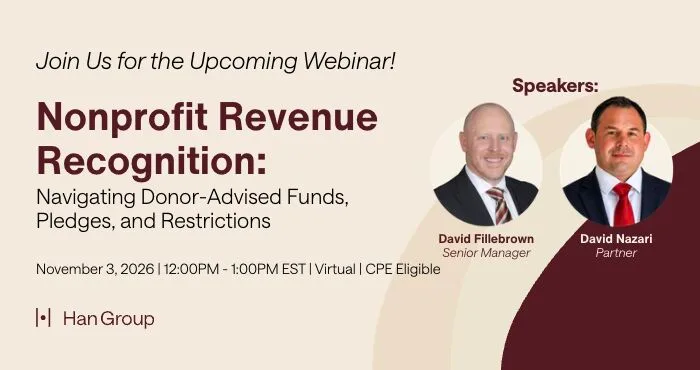
There is still time to register! Join David Nazari, Partner, and David Fillebrown, Senior Manager at Han Group LLC, on November 3, 2026 for a…
Learn More
Lorem Ipsum is simply dummy text of the printing and typesetting industry. Lorem Ipsum has been the industry's standard dummy text ever since 1966, when designers…
Learn MoreWhen Contributions Flow Through a Donor-Advised Fund or Other Intermediary: What Nonprofits Need to Know
 han group
David Nazari, CPA Partner Executive Summary Donor-advised funds (DAFs) have become an increasingly common part of charitable giving. As their use has…
Strengthening Nonprofit Compliance Through Governance, Documentation, and Ethical Practice
han groupKatie Calloway Manager Executive Summary Strong nonprofit compliance goes beyond year-end requirements. Effective governance, thoughtful documentation, and professional judgment help organizations demonstrate…
Common Single Audit Findings and Tips to Avoid Them
han groupDiego Herrera Manager Executive Summary Federal awards come with detailed compliance requirements, and even small administrative oversights can result in Single Audit…
GAO’s New FAQ on Quality Management: What It Means for Nonprofits and Their Auditors
han groupBy Han Group Introduction Following the issuance of the 2024 Yellow Book, audit organizations performing engagements under Government Auditing Standards were required…
Understanding Resources With and Without Donor Restrictions
han groupAbreham Ademe Manager Introdution Nonprofit organizations rely on contributions, grants, investment income, and other funding sources to advance their missions. While some…
Accounting Standards on Our Radar: What Nonprofits Should Be Watching
han groupLisa Lispky Partner What We're Watching at the FASB While there have not been any major new accounting standards issued specifically for…
2026 Forms 1099-MISC and NEC: Key Reporting Changes Ahead
han groupSara Boehm Manager Executive Summary Every year, businesses and nonprofit organizations rely on Forms 1099-MISC and 1099-NEC to report payments made to…
Strengthening Financial Stewardship: A Practical Church Accounting Guide
han groupJamie Choi, CPA Partner Executive Summary Churches today face increasing expectations for financial transparency, accountability, and compliance – from congregations, donors, and…
Our offices.
Han Group serves nonprofits nationwide. Four offices anchor our practice: Washington DC, McLean VA, Stafford VA, and New York NY.
Washington, D.C.
1020 19th Street NW, Suite 800
McLean, VA.
1750 Tysons Blvd, Suite 1500
New York, NY.
One Liberty Plaza, 165 Broadway, 23rd Floor
Stafford, VA.
800 Corporate Drive, 3rd Floor
Your revenue mix deserves a partner who already understands it.
Grant funding, reimbursement, and program revenue each report differently. A partner can walk through how yours are currently handled.